

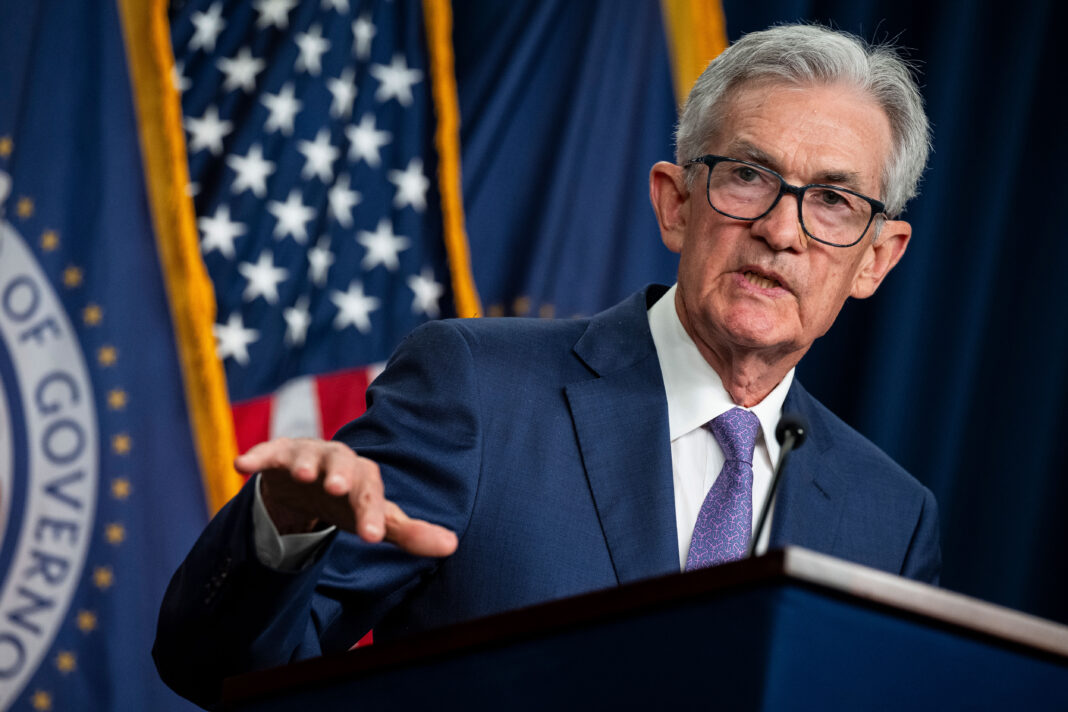
Federal Reserve officials announced Wednesday that they expect to cut their benchmark interest rate once this year because inflation remains persistently elevated.
Dek Terrell, director of the LSU Center for Economics, Business & Policy Research, says the latest announcement is good news, but it is contingent on a few things.
“It’s good news as far as prices are not increasing again by a significant amount,” he says. The only problem is they’re still high. Many individuals are going out to the supermarket, going out to a restaurant, or paying rent and those prices have gone up and the wages haven’t necessarily caught up with that.”
Inflation has cooled in the past two months, and the Fed characterizes the economy as growing at a solid pace while hiring has “remained strong.”
Employers are facing issues because wages have not kept up with the rise in expenses for most consumers.
“They’re having employees come in and say they need a raise to catch up with this,’ Terrell says. “One of the problems the Fed has is they’re trying to balance concerns about another wave of inflation.”
He notes that if workers get the wages that they want or need to keep up with spending, and if employers pass that to consumers, waves of inflation could ensue.
The 30-year mortgage rates fell below 7% at one point Wednesday, and there is hope that they will tumble further. Those declines could help more people buy and sell homes.
According to Terrell, mortgage rates were historically low from 2010 to 2021, but current rates are not high relative to historic mortgage or interest rates.
“Interest rates were higher than they were in recent years for much of the period, from 1970 to 2010, so I don’t think you can necessarily assume that rates will go back down to a 3% or 4% mortgage rate,” he says. “Maybe 5% is more of the long-run equilibrium.”
He notes that the stock market is hitting record highs because investors believe AI will significantly impact productivity. The economist says some Baton Rouge area firms could become more productive and benefit from better technology over time as new technologies are introduced.
“If it makes individual workers more productive as well, they should see really rapid wage gains, but employers are only going to be able to pay those really rapid wage gains once employees actually become more productive,” Terrell says. “I think for the economy to be a successful economy, wages for the overwhelming majority of people need to rise at least as fast as prices are, perhaps a little faster to reflect productivity gains.”
